
By Lara Sinclair
Retirement Income Optimiser is designed to support your overall retirement income by potentially improving Age Pension outcomes in retirement, if you choose to start a lifetime pension issued by CFS.
Summary
Retirement Income Optimiser is a feature of FirstChoice super. In conjunction with a CFS lifetime pension and the Age Pension, it may help eligible members increase their income in retirement. Learn how it works.
Retirement Income Optimiser is a new feature of FirstChoice super that may help eligible members optimise their income once they retire, if they choose to commence a CFS lifetime pension.
It’s not a new investment option. It doesn’t change the way your money is invested. And it doesn’t affect your fees or insurance.
It simply operates in the background of your eligible FirstChoice super account.
Then later, when you retire, the Retirement Income Optimiser may result in more favourable Age Pension entitlements from Centrelink, if you choose to commence a CFS lifetime pension, immediately or in the future, depending on your circumstances.
What does the Retirement Income Optimiser actually do?
The Retirement Income Optimiser enables eligible members to access a potentially more favourable way of having a future CFS lifetime pension assessed by Centrelink for Age Pension entitlements.
Under the Centrelink assets test, instead of looking at your actual super balance (inclusive of actual investment earnings), Centrelink uses an alternative balance based on a ‘deemed’ rate of investment earnings.
Depending on your personal circumstances, including the performance of your investments and the rules applying at the time, this treatment may result in a lower calculated balance, and potentially higher Age Pension payments, compared with not using the Retirement Income Optimiser and CFS lifetime pension.
CFS is currently developing the CFS lifetime pension product, which is expected to be released as early as 2027.
How does the Retirement Income Optimiser work?
The Retirement Income Optimiser is essentially an accounting feature. While it is active, an alternative balance is calculated, based on contributions and deemed investment earnings rather than your account balance.
If you later (once eligible) choose to commence a CFS lifetime pension either immediately or in the future, Centrelink will use this alternative balance to calculate your level of assessable assets for the Age Pension assets test instead of the amount invested in the lifetime pension.
Because the alternative balance may be lower than your actual account balance, this could improve your Age Pension outcome and increase your overall retirement income. This will depend on your circumstances and the rules at the time.
The longer the feature is active in your super before you choose (once eligible) to commence a CFS lifetime pension (immediately or in the future), the greater the potential benefit may be.
Importantly, the Retirement Income Optimiser doesn’t carve out or lock away your money. You remain invested in your selected FirstChoice options.
When you reach retirement or satisfy another specified condition of release, you can choose whether to use a CFS lifetime pension or not.
Not a CFS member? Make the switch today
If your super could be doing more, switching is easier than you think. Join CFS super online – it takes less than 10 minutes.
How super, the Retirement Income Optimiser and the Age Pension work together
In retirement, many Australians switch their super to an account-based pension, which provides flexible, tax-free access to your money.
A lifetime pension doesn’t have to replace your account-based pension. It can work alongside an account-based pension to provide an income stream that won’t run out.
Together, this can mean:
- income for life, from the lifetime pension
- flexible access and growth, from the account-based pension
- possible Age Pension support, if you’re eligible.
When determining your Age Pension eligibility under the assets test, Centrelink will look at the balance in an account-based pension.
When Centrelink looks at an innovative retirement income stream (IRIS), such as the CFS lifetime pension, it will assess:
- 60% of the alternative balance when the lifetime pension starts, and
- 30% of the alternative balance later in life (typically from around age 85).
Because Centrelink uses the alternative balance and only assesses a proportion of this amount, it may help you qualify for a higher Age Pension under the assets test, compared with only having an account-based pension in retirement. Whether it does will depend on your personal situation, the performance of your investments, the product rules, and the government rules at the time.
Under the income test, 60% of any payments from a CFS lifetime pension is assessable income. In contrast, most account-based pensions are treated like other financial investments and subject to deeming for income test purposes
Case study: Harry, aged 47, with a super balance of $200,000
Harry is 47 and has $200,000 in a FirstChoice Wholesale Personal Super account. His employer makes super guarantee contributions based on an annual salary of $100,000 p.a.
The built-in Retirement Income Optimiser feature is working in the background until he retires. At age 65 he meets a condition of release and advises his super fund that he would like to delay commencing a lifetime pension until he retires at age 67.
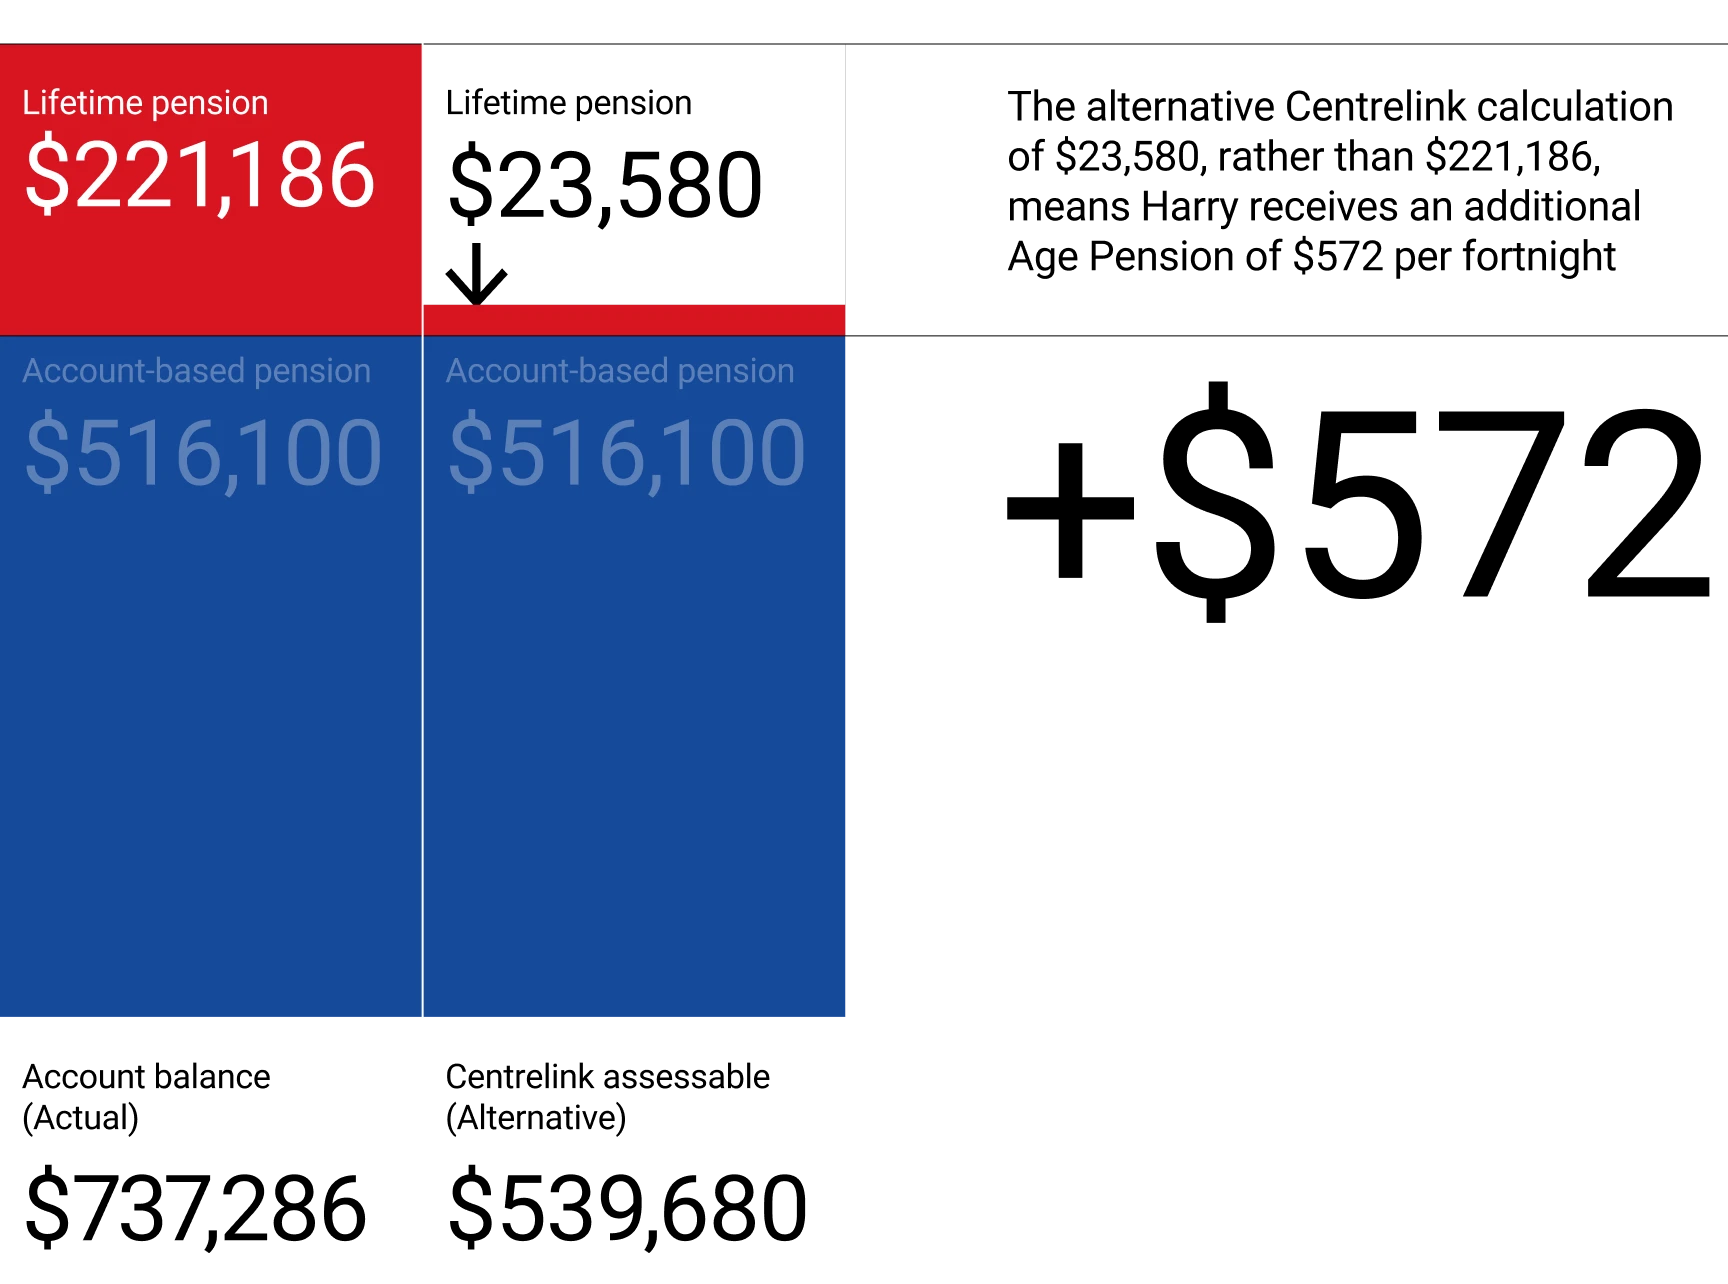
Harry’s super balance has grown to $737,286.
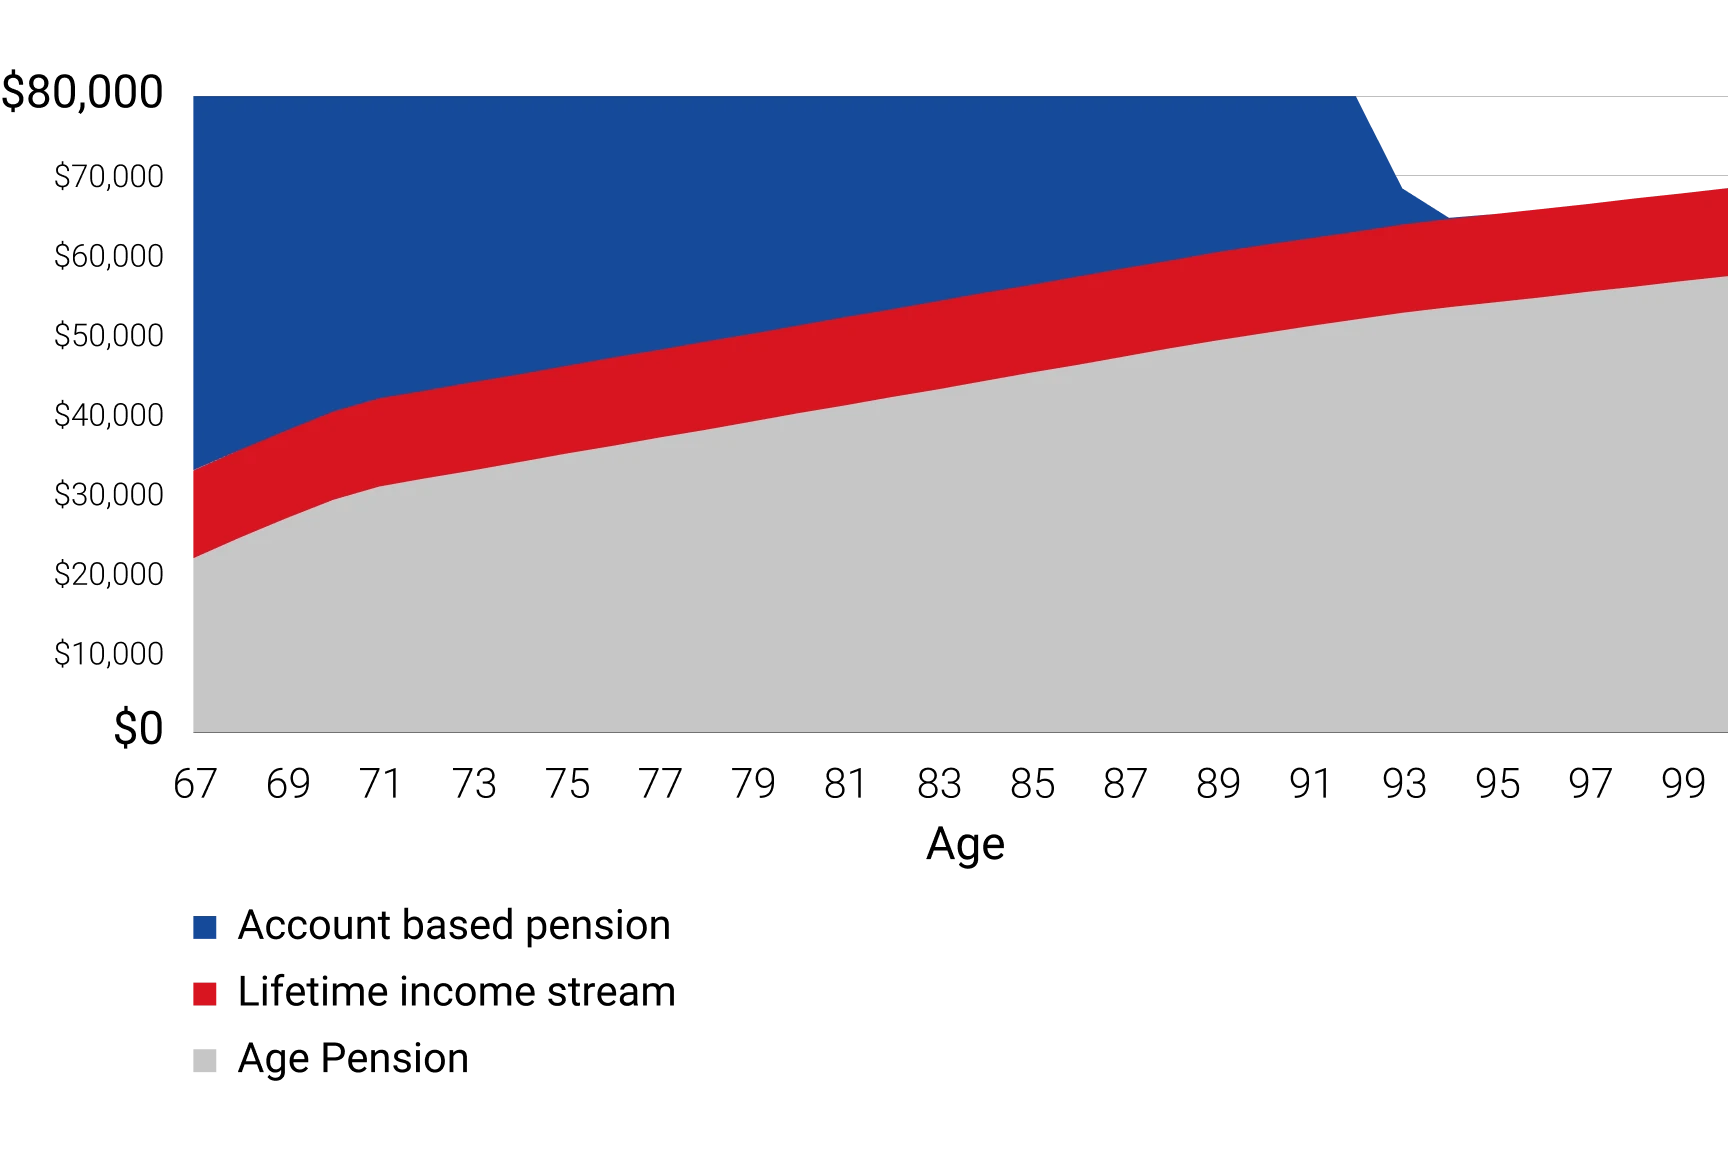
He decides to purchase an account-based pension with 70% of his super balance and he allocates the remaining 30% to the lifetime pension.
Due to the Retirement Income Optimiser feature and the concessional asset test rules that apply when Centrelink assesses lifetime pensions, only $23,580 gets assessed. This results in Harry receiving an additional $572 per fortnight in Age Pension.
For illustrative purposes only. This example is intended to demonstrate how Retirement Income Optimiser could affect Age Pension outcomes based on the assumptions set out. Actual outcomes will depend on individual circumstances. This example uses a number of assumptions and may not reflect the actual outcomes of any particular person. It is based on our understanding of relevant laws and regulations and is subject to change. The information is of a general nature only. It is not intended to constitute financial, taxation or legal advice and should not be relied on as such1.
Retirement outcomes may differ
Depending on a person's circumstances, commencing a CFS lifetime pension after meeting a Specified Condition of Release may result in the pension becoming assessable for Centrelink or DVA purposes earlier than if the benefit remained in accumulation, which may affect their or their partner's income support entitlements.
Who is eligible for the Retirement Income Optimiser feature?
FirstChoice Wholesale Personal Super and FirstChoice Employer Super members are eligible for the Retirement Income Optimiser feature to be applied to your account if:
- you are aged 17 or over;
- you are under age 58; and
- you have not already met a Specified Condition of Release.
How can I switch on the Retirement Income Optimiser?
Eligible members in FirstChoice Wholesale Personal Super will have the feature automatically switched on, with the option to opt out at any time.
Eligible FirstChoice Employer Super members can choose to opt in through FirstNet.
Not sure if the Retirement Income Optimiser has been turned on for your super? Login to FirstNet to check
Want to know more about whether the Retirement Income Optimiser is right for you?
The Retirement Income Optimiser allows eligible super balances to be treated differently for Age Pension calculations if you later choose to commence a CFS lifetime pension either immediately or in the future. However, depending on individual circumstances, the alternative calculations may not change your social security outcome if:
- you already qualify for the maximum Age Pension throughout retirement because of limited assets and income; or
- you would not qualify for the Age Pension at all throughout retirement due to significant assets or income; or
- your Age Pension will be determined under the income test throughout retirement.
Consider speaking to a financial adviser to understand how this feature may apply to you. Explore your financial advice options
How much retirement bonus could you get at CFS?
See how much the CFS Pension Bonus could add to your starting balance in retirement. We've crunched the numbers and come up with a table of estimated amounts, for balances starting at $200,000.
Frequently asked questions
No. There is no additional cost to have the Retirement Income Optimiser applied to your account.
No. Retirement Income Optimiser preserves a future option. You do not need to make a lifetime pension decision until you meet a Specified Condition of Release.
As a FirstChoice Employer Super member, opting in to Retirement Income Optimiser will change your account from ‘MySuper’ to ‘Choice’ but your fees, services, insurance and investment options stay the same.
No. Your investment options, contribution strategy, account fees and insurance, where applicable, continue as normal.
No. No money is set aside while you remain in super. Withdrawals, rollovers or transfers can still be made where permitted, although they may reduce any potential Age Pension benefits. If you choose to commence a lifetime pension at retirement (or when you meet another specified condition of release), restrictions on accessing your money and death benefits may apply. These restrictions will be outlined in information on the lifetime pension product for you to consider.
Depending on a person's circumstances, commencing a CFS lifetime pension after meeting a Specified Condition of Release may result in the pension becoming assessable for Centrelink purposes earlier than if the benefit remained in accumulation, which may affect income support entitlements. This treatment also applies if you or your partner receive an income support payment from the DVA, such as the Service Pension.
It should be noted that if you meet a Specified Condition of Release and elect to commence a CFS lifetime pension with the Retirement Income Optimiser (either immediately, or at a later date), the lifetime pension may be assessable for Centrelink or DVA purposes from the date you meet the condition of release.
Yes, you can opt out at any time. If you opt out, the separately tracked alternative balance will not be available for use with a future CFS lifetime pension.
The alternative balance amount is not portable to another super fund. If you roll your account away from CFS, the feature and its separately tracked alternative balance will not move to the receiving fund.
No. CFS is still developing a lifetime pension product, which is expected to be released as early as 2027.
What's next?

Retirement Income Optimiser
Who is eligible and how could it affect your retirement income?

Thinking of retiring soon?
Our Grow into Retirement guide can help you maximise your super.

Retire with confidence
We’re here to help guide you throughout your retirement journey.
¹ All results in today’s dollars (assuming CPI 2.5% p.a.).
Lifetime pension: 5% per annum annual payment indexed to CPI of 2.5%. As the lifetime pension product is not yet available in FirstChoice, this lifetime pension projection is for illustrative purposes only and does not represent the product features or recommendation on the annual payment rate.
SG 12% on salary of $100,000 indexed at 3.7%
Earning rate 6.2% (net of tax and fees) from age 47 to 65, and 6.7% p.a. (net of fees) from age 65 in accumulation super and account-based pension
Assumed upper deeming rate 5% p.a. At age 67, deemed alternative balance $555,400 less account-based pension commutation $516,100 = $39,300. Centrelink assessable asset value = 60% x $39,300 = $23,580.
Age pension calculation assumes $10,000 other assets and single homeowner
Additional Age Pension of $572 per fortnight at age 67 compares Age Pension if superannuation 100% assessable in an account-based pension, compared to Age Pension if 30% invested in lifetime pension using the Retirement Income Optimiser feature and 70% in an account-based pension.
Age pension rates and thresholds current as at May 2026.
Retirement income projection assumes Harry requires $80,000 p.a. (today’s dollar) in retirement from a combination of account-based pension, lifetime pension and Age Pension.
For illustrative purposes only. This example is intended to demonstrate how Retirement Income Optimiser could affect Age Pension outcomes based on the assumptions set out below. Actual outcomes will depend on individual circumstances.
Disclaimer
Avanteos Investments Limited ABN 20 096 259 979, AFSL 245531 (AIL) is the trustee of the Colonial First State FirstChoice Superannuation Trust ABN 26 458 298 557 and issuer of FirstChoice range of super and pension products. Colonial First State Investments Limited ABN 98 002 348 352, AFSL 232468 (CFSIL) is the responsible entity and issuer of products made available under FirstChoice Investments and FirstChoice Wholesale Investments.
Information on this webpage is provided by AIL and CFSIL. It may include general advice but does not consider your individual objectives, financial situation, needs or tax circumstances. You can find the target market determinations (TMD) for our financial products at https://www.cfs.com.au/tmd which include a description of who a financial product might suit. You should read the relevant Product Disclosure Statement (PDS) and Financial Services Guide (FSG) carefully, assess whether the information is appropriate for you, and consider talking to a financial adviser before making an investment decision. You can get the PDS and FSG at www.cfs.com.au or by calling us on 13 13 36.