
Enhance your retirement options, without changing your super.
What is Retirement Income Optimiser?
Making your super last in retirement is a big focus for many Australians.
Retirement Income Optimiser is a feature of FirstChoice super. It’s designed to support your overall retirement income by potentially improving Age Pension outcomes in retirement, if you choose to start a lifetime pension issued by CFS.
Key benefits

Keeps more retirement income options open

Potentially improves your Age Pension outcomes

Doesn’t change your super investments or fees
How Retirement Income Optimiser works now
Once Retirement Income Optimiser is switched on, it works in the background of your super account. At this stage, nothing changes. Your fees, investment options, insurance (if applicable) and account features will not change.
What does change is the way Centrelink will assess your super balance in the future if you choose to start a lifetime pension issued by CFS – which could potentially increase your eligibility for the Age Pension and provide more income in retirement (see below).
Switching it on or off
- As a FirstChoice Wholesale Personal Super member you don’t have to do anything. Retirement Income Optimiser is automatically switched on for eligible members in FirstChoice Wholesal Personal Super. You can choose to opt out at any time.
- As a FirstChoice Employer Super member, you need to actively choose to opt in to Retirement Income Optimiser. By doing so, there will be no changes to your existing account features – including your fees, services, insurance and investment options.
To opt in or out of Retirement Income Optimiser
- Log in to FirstNet.
- If you see a Retirement Income Optimiser banner on the top, click on Opt in now. (FirstChoice Employer Super Plan members only).
- Select Retirement Income Optimiser from the menu on the left.
- Follow the prompts.
How Retirement Income Optimiser works at retirement
When you retire or meet another eligible condition of release, and you choose to start a CFS lifetime pension, it will pay you an income for life that can either start immediately, or at a later date (deferred). If Retirement Income Optimiser is switched on for your super, based on the current rules, Centrelink assesses your super account balance differently when calculating your Age Pension.
Instead of looking at your actual super balance (inclusive of actual investment earnings), Centrelink uses an alternative balance based on a ‘deemed’ rate of investment earnings, which is usually lower.
Depending on your situation, this may increase your Age Pension. If you don’t choose to start a CFS lifetime pension, your super continues as normal. The choice is yours, having regard to your circumstances at the time.
Important things to know
- The longer Retirement Income Optimiser applies to your account, the higher the potential Age Pension effect may be (depending on your circumstances and Centrelink rules at the time).
- You can opt out of Retirement Income Optimiser. However, if you opt out and later choose to take up a lifetime pension issued by us, the different. Centrelink treatment won’t apply when calculating the assessable asset value of the lifetime pension (i.e. the value of the pension using the deemed rate of investment earnings). This may reduce any potential Age Pension benefit compared with having the feature switched on.
- CFS is still developing a lifetime pension product, which is expected to be released as early as 2027.
- Lifetime pension products are subject to capital access schedule limits in accordance with legislation.
- Whether this feature is right for you depends on your personal circumstances.
For more information, see the FirstChoice super Product Disclosure Statement or speak to a financial adviser.
Questions about Retirement Income Optimiser?
You don’t have to work it out on your own. As a CFS member, you can get general advice on your FirstChoice super from our experienced super and retirement guidance consultants at no extra cost.
Our team can explain how Retirement Income Optimiser works, answer your questions and help you understand your broader super and retirement options.
What is a CFS lifetime pension?
CFS lifetime pension is our new retirement income product, expected to launch as early as 2027. It’s designed to give you greater certainty by paying you a regular income for life.
This type of ‘Innovative Retirement Income Stream’ is typically eligible for concessional treatment under the Age Pension assets test, which may help improve your Age Pension outcomes.
How it works with other pension products
Think of a CFS lifetime pension as one piece of your retirement picture. It can work alongside:
- an account-based pension, which can provide flexible, tax-free access to your money (depending on your circumstances and eligibility rules), and
- the Age Pension, which can provide income from the government if you’re eligible.
The examples below show how this can work in practice.

See how Retirement Income Optimiser could affect Age Pension outcomes at retirement
Harry is 47 and has $200,000 in a FirstChoice Wholesale Personal Super account. His employer makes super guarantee contributions based on a salary of $100,000 p.a.
The built-in Retirement Income Optimiser feature is working in the background until he retires. At age 65 he meets a condition of release and advises his super fund that he would like to delay commencing a lifetime pension until he retires at age 67.
For illustrative purposes only. This example is intended to demonstrate how Retirement Income Optimiser could affect Age Pension outcomes based on the assumptions set out below. Actual outcomes will depend on individual circumstances.
Harry’s super at 67
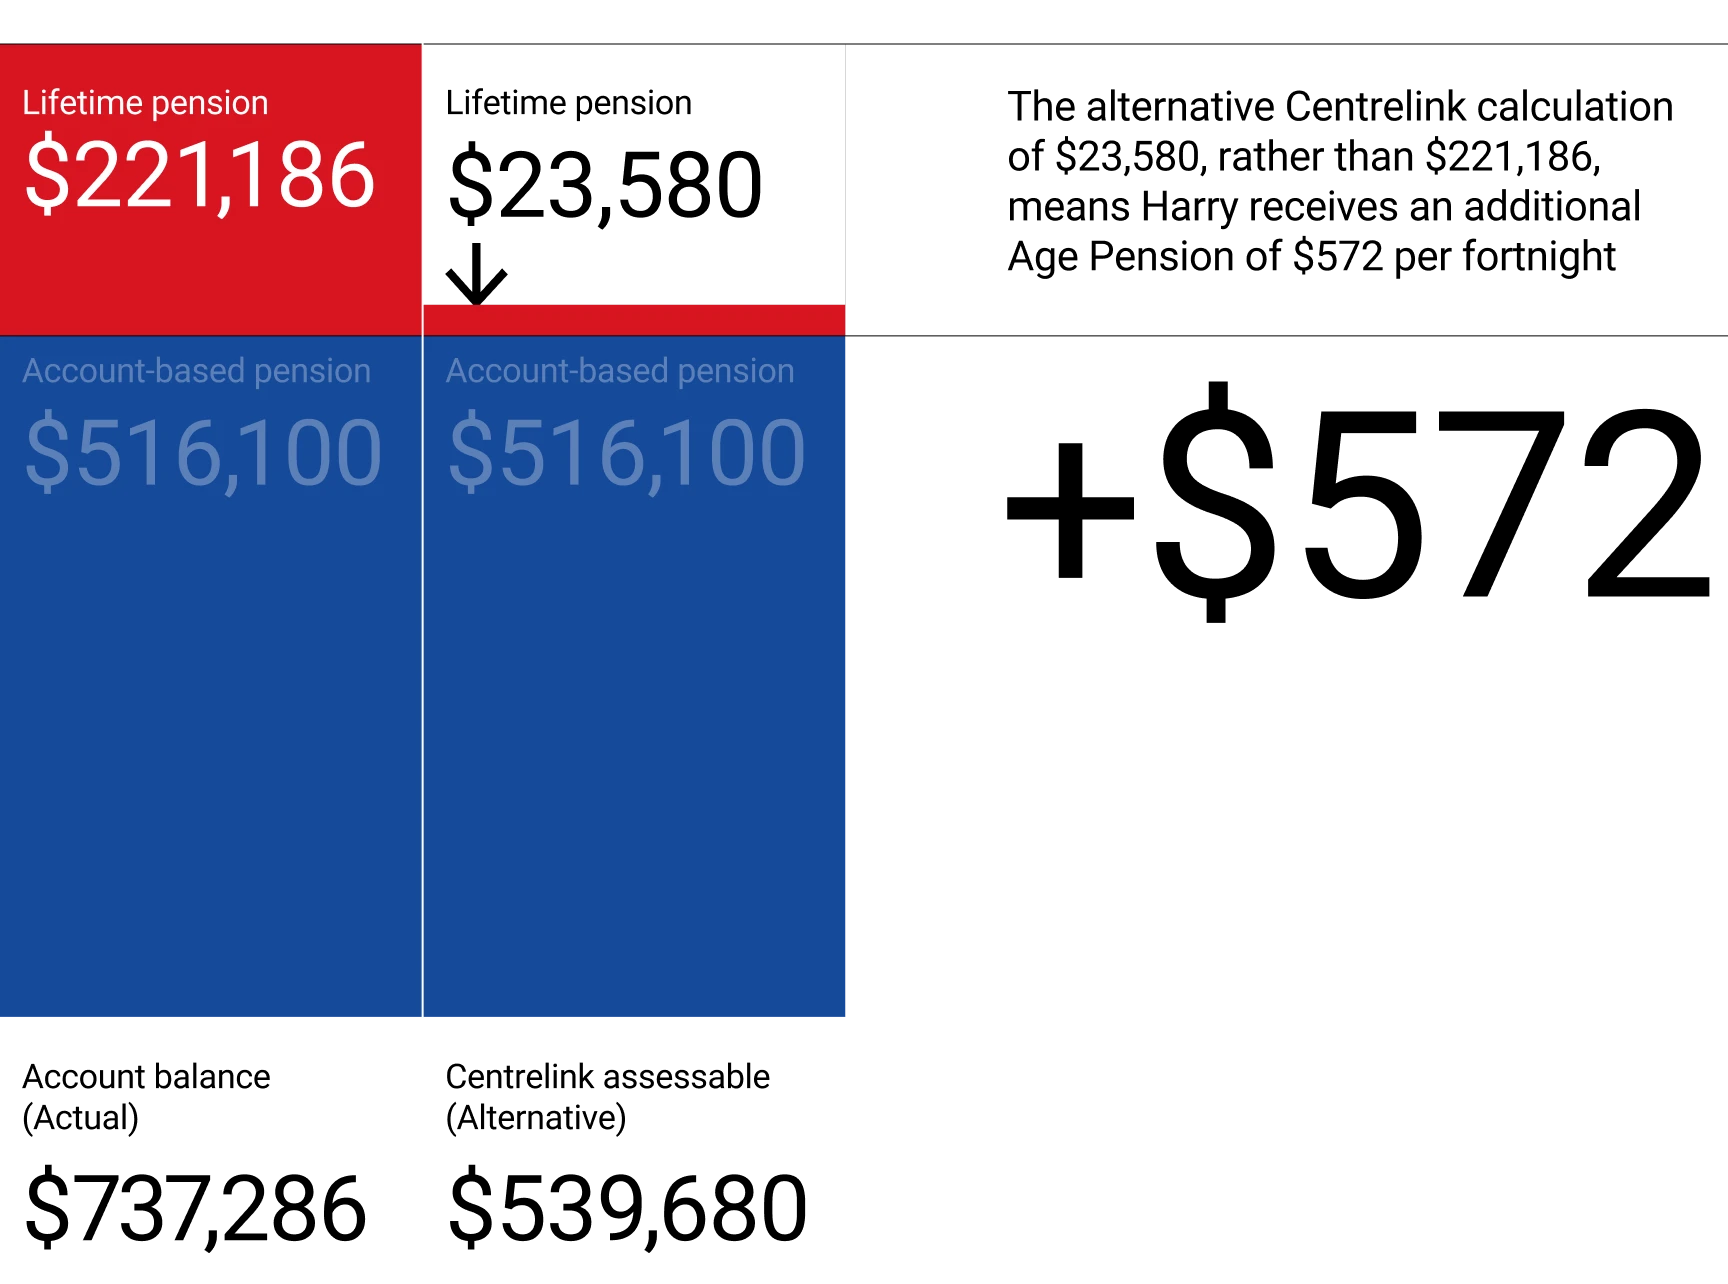
Harry’s super balance has grown to $737,286.
He decides to purchase an account-based pension with 70% of his super balance and he allocates the remaining 30% to the lifetime pension.
Due to the Retirement Income Optimiser and the concessional asset test rules that apply when Centrelink assesses lifetime pensions, only $23,580 gets assessed. This results in Harry receiving an additional $572 per fortnight in Age Pension.
Retirement outcomes may differ
Depending on a person's circumstances, commencing a CFS lifetime pension after meeting a Specified Condition of Release may result in the pension becoming assessable for Centrelink or DVA purposes earlier than if the benefit remained in accumulation, which may affect their or their partners income support entitlement.
Harry’s retirement income projection
Harry’s income in retirement is a mix of income from his account-based pension, lifetime pension and the Age Pension, with the lifetime pension and Age Pension providing an income for life.
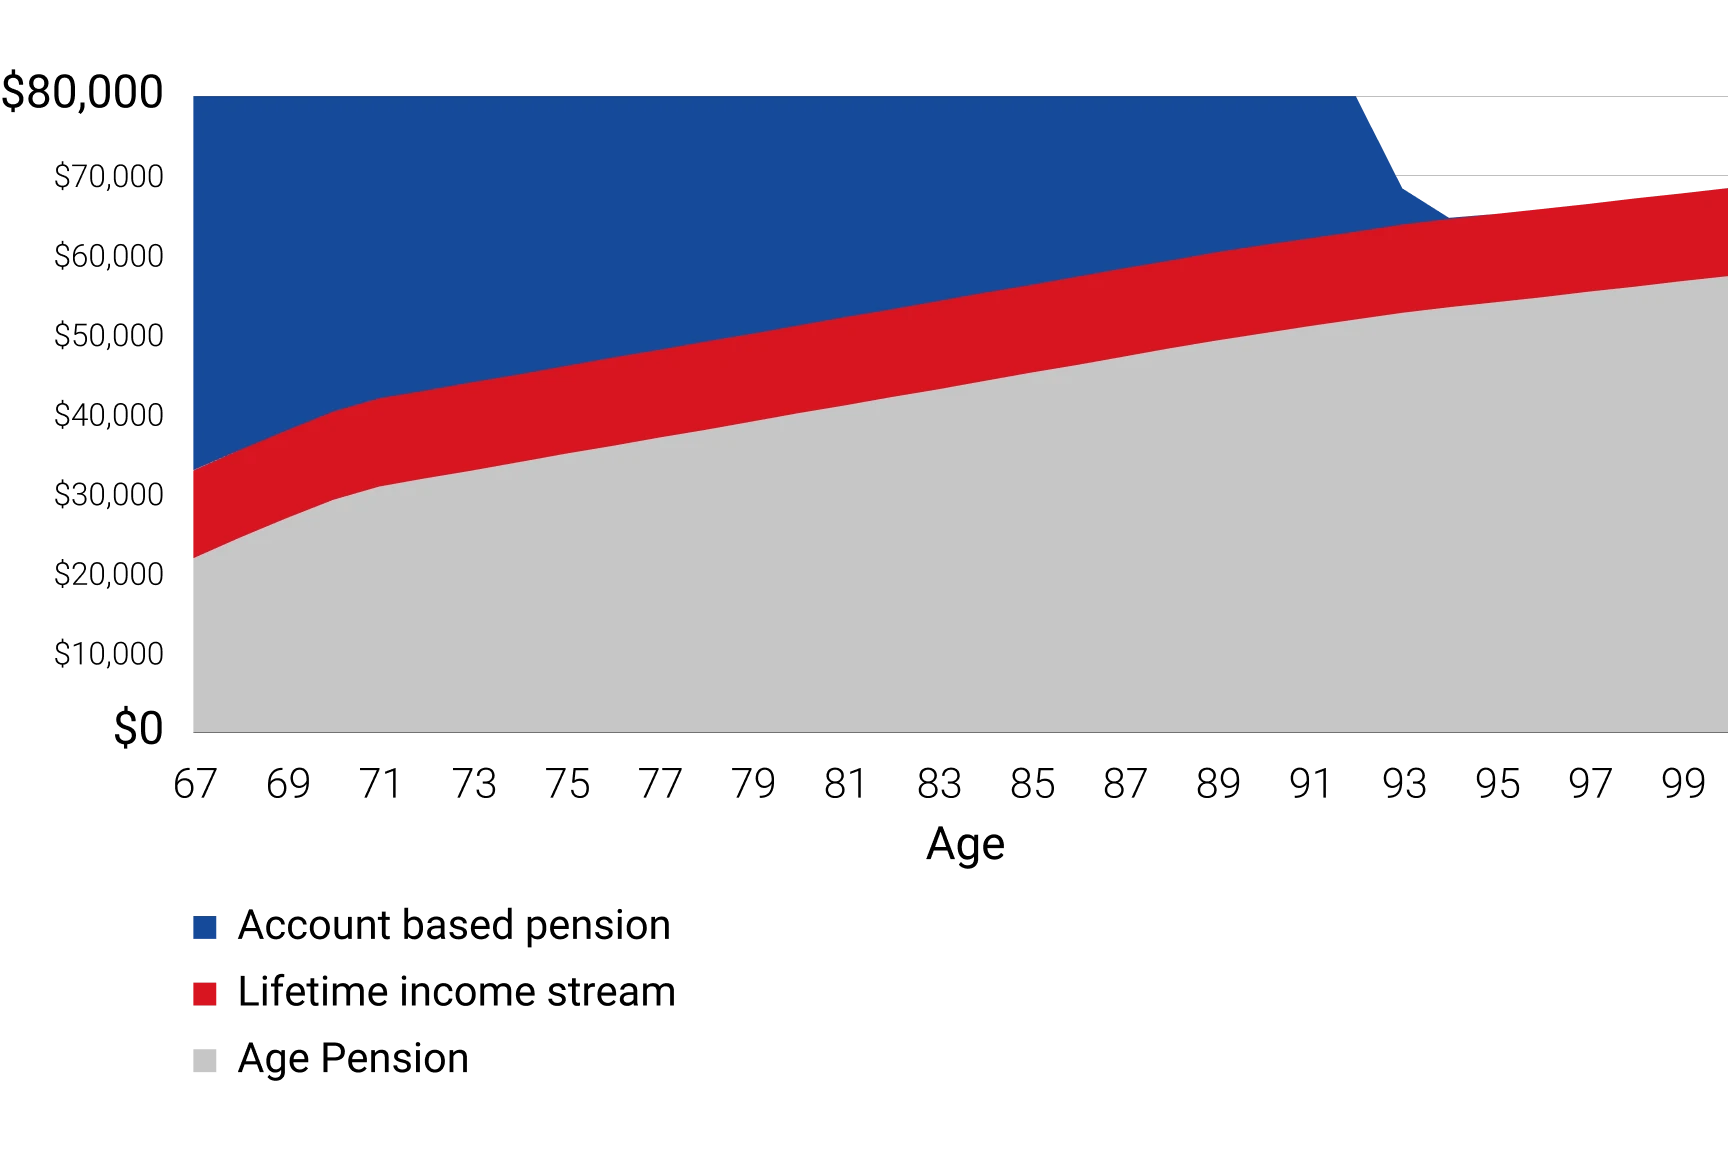
This example uses a number of assumptions and may not reflect the actual outcomes of any particular person. It is based on our understanding of relevant laws and regulations as at May 2026 and is subject to change.
- All results in today’s dollars (assuming CPI 2.5% p.a.).
- Lifetime pension: 5% per annum annual payment indexed to CPI of 2.5%. As the lifetime pension product is not yet available in FirstChoice, this lifetime pension projection is for illustrative purposes only and does not represent the product features or recommendation on the annual payment rate.
- SG 12% on salary of $100,000 indexed at 3.7%
- Earning rate 6.2% (net of tax and fees) from age 47 to 65, and 6.7% p.a. (net of fees) from age 65 in accumulation super and account-based pension
- Assumed upper deeming rate 5% p.a. At age 67, deemed purchase amount $555,400 less account-based pension commutation $516,100 = $39,300. Centrelink assessable asset value = 60% x $39,300 = $23,580.
- Age pension calculation assumes $10,000 other assets and single homeowner
- Additional Age Pension of $572 per fortnight at age 67 compares Age Pension if superannuation 100% assessable in an account-based pension, compared to Age Pension if 30% invested in lifetime pension using the Retirement Income Optimiser feature and 70% in an account-based pension.
- Retirement income projection assumes Harry requires $80,000 p.a. (today’s dollar) in retirement from a combination of Age Pension, lifetime pension and Age Pension.
Part of your CFS Retirement Advantage™
At CFS, we bring together retirement products, tools, expert guidance and advice – helping you understand your options and make informed decisions about your future.
Frequently asked questions
As a FirstChoice Employer Super member, opting in to Retirement Income Optimiser will change your account from ‘MySuper’ to ‘Choice’ but your fees, services, insurance and investment options stay the same.
No. There is no additional cost to have Retirement Income Optimiser applied to your super account.
No. Your super continues to operate as a standard super account, with the same investment choice, flexibility and features you already have. Retirement Income Optimiser does not restrict how you invest your super.
No. It is a feature within your super account that may support better Age Pension outcomes if you later choose to commence a CFS lifetime pension.
Depending on your circumstances and Centrelink rules at the time, the beneficial asset test treatment from having Retirement Income Optimiser switched on will also apply to other Government pensions, such as the Disability Support Pension and Service Pension from the Department of Veterans’ Affairs.
Depending on a person's circumstances, commencing a CFS lifetime pension after meeting a Specified Condition of Release may result in the pension becoming assessable for Centrelink or DVA purposes earlier than if the benefit remained in accumulation, which may affect your or your partners income support entitlements. This treatment also applies if you or your partner receive an income support payment from the Department of Veterans’ (DVA) such as the Service Pension.
It should be noted that if you meet a Specified Condition of Release and elect to commence a CFS lifetime pension with the Retirement Income Optimiser (either immediately, or at a later date), the lifetime pension may be assessable for Centrelink or DVA purposes from the date you meet the condition of release.
No. Your super remains accessible where permitted under the usual superannuation rules. Retirement Income Optimiser does not lock your money away or reduce your flexibility any further.
However, any permissible withdrawals, rollovers or transfers may reduce any potential Age Pension benefit if you later start an eligible lifetime pension issued by us.
FirstChoice Wholesale Personal Super and FirstChoice Employer Super members will be eligible for Retirement Income Optimiser to be applied to your account if:
- you're aged 17 or over
- you’re under age 58, and
- you haven’t already met a Specified Condition of Release, including:
- being permanently incapacitated or having a terminal medical condition
- reaching age 60 and permanently retiring
- ceasing a gainful employment arrangement after reaching age 60, or
- reaching age 65.
Once Retirement Income Optimiser is applied to your account, the feature will continue to apply (if eligible) when you reach age 58 or over, unless you choose to opt out. However, if you meet a Specified Condition of Release and a lifetime pension is not available, this feature will be switched off without affecting your super account. The feature will also be switched off if your account is closed.
Retirement Income Optimiser allows eligible super balances to be treated differently for Age Pension calculations if you later move into an eligible lifetime pension. However, depending on individual circumstances, the alternative calculations may not change your social security outcome if you already qualify for the maximum Age Pension throughout retirement because of limited assets and income, or you would not qualify for the Age Pension at all throughout retirement due to significant assets or income. You should consider speaking to a financial adviser to understand how this feature may apply to you.
We're here to help
Get in touch
Get in touch with us online or call us 8:30am to 6pm (Sydney time) Monday to Friday.
Find the right advice option
Our dedicated team can help you choose from a range of different financial advice options.
Download mobile app
Track your balance and see your transaction history from anywhere.
Disclaimer
Avanteos Investments Limited ABN 20 096 259 979, AFSL 245531 (AIL) is the trustee of the Colonial First State FirstChoice Superannuation Trust ABN 26 458 298 557 and issuer of FirstChoice range of super and pension products. Colonial First State Investments Limited ABN 98 002 348 352, AFSL 232468 (CFSIL) is the responsible entity and issuer of products made available under FirstChoice Investments and FirstChoice Wholesale Investments.
Information on this webpage is provided by AIL and CFSIL. It may include general advice but does not consider your individual objectives, financial situation, needs or tax circumstances. You can find the target market determinations (TMD) for our financial products at https://www.cfs.com.au/tmd which include a description of who a financial product might suit. You should read the relevant Product Disclosure Statement (PDS) and Financial Services Guide (FSG) carefully, assess whether the information is appropriate for you, and consider talking to a financial adviser before making an investment decision. You can get the PDS and FSG at www.cfs.com.au or by calling us on 13 13 36.