
A bigger balance for your clients, from day one
Reward clients for entering retirement with CFS. A simple, automatic bonus paid at pension commencement that can improve retirement outcomes while fitting naturally within the advice journey.
A simple way to add value at the retirement moment
Pension Bonus rewards your clients for retiring with CFS. It lands automatically at pension commencement, so you deliver a tangible uplift from day one.

More in your client's pension
An immediate one-off boost added to the pension starting balance. A clear, quantifiable benefit you can put in front of clients at the point of transition.

Advice stays in your hands
You determine the right retirement strategy for your client. Where the eligibility requirements are met, Pension Bonus adds further value to the transition.

Automatic, not another task
Paid automatically when eligibility is met at commencement. Nothing extra to apply for, it works within your existing advice process.
Three steps, no extra advice work
Pension Bonus is available when your client moves from FirstChoice Wholesale Super, TTR or FirstChoice Employer into a FirstChoice Wholesale Pension.

Client holds eligible super
Your client holds an eligible CFS super account older than 90 days, invested in an eligible option (cash and cash-like options are excluded).

Move to pension
They commence a FirstChoice Wholesale Pension with a like-for-like transfer of their eligible balance, up to the Transfer Balance Cap.

Bonus paid automatically¹
The bonus, the eligible balance × the current rate, is added to the pension starting balance automatically on commencement.
A set rate, reviewed regularly
Pension Bonus is based on a single rate (currently 0.80%), reviewed regularly and published here. It's paid on the total eligible balance transferred, up to the client's Transfer Balance Cap, and counts towards that cap. Adviser estimates are available in FirstNet Adviser for clients over 50.
What the bonus looks like in practice
Eligible balance (incl. buy/sell refund of $500)
$450,500
Pension Bonus rate
0.80% (0.008)
Ineligible SuperFirst Transfer Facility (cash)
excluded
Pension Bonus paid
$3,604
$450,500 × 0.80% = $3,604
The bonus is added to your client's pension starting balance. In this example, the purchase price becomes the total balance plus the buy/sell refund, plus the Pension Bonus (around $454,104), less any other adjustments such as advice fees.
Only eligible balances count. Amounts in cash or cash-like options, including money rolled in via the SuperFirst Transfer Facility, are excluded from the calculation2.
Eligibility at a glance
A quick reference for identifying Pension Bonus eligibility in client conversations3.

90-day account tenure
Your client must move at least one account older than 90 calendar days to pension.

Eligible investment options
Cash and cash-like options are excluded, including FSI Strategic Cash and SuperFirst Transfer Facility money. See table below for more detail.

Once per lifetime
Each client can receive one bonus per lifetime. If multiple pensions start on the same day, all accounts are assessed for eligibility.

Like-for-like transfer
The investment option held in super or pre-retirement must also be available in the pension.
The Pension Bonus is calculated only on qualifying investment options transferred into the pension. The following are excluded from the calculation:
FirstChoice Wholesale Personal Super
- SuperFirst Transfer Facility (underlying First Sentier Strategic Cash)
- First Sentier Strategic Cash
- FirstRate Saver
- FirstRate Saver non-auto rebalancing
- All FirstRate Term Deposit options
FirstChoice Wholesale Pre-retirement Pension
- FirstRate TTR Saver
- FirstRate TTR Saver non-auto rebalancing
- First Sentier TTR Strategic Cash
FirstChoice Employer Super
- FirstRate Saver
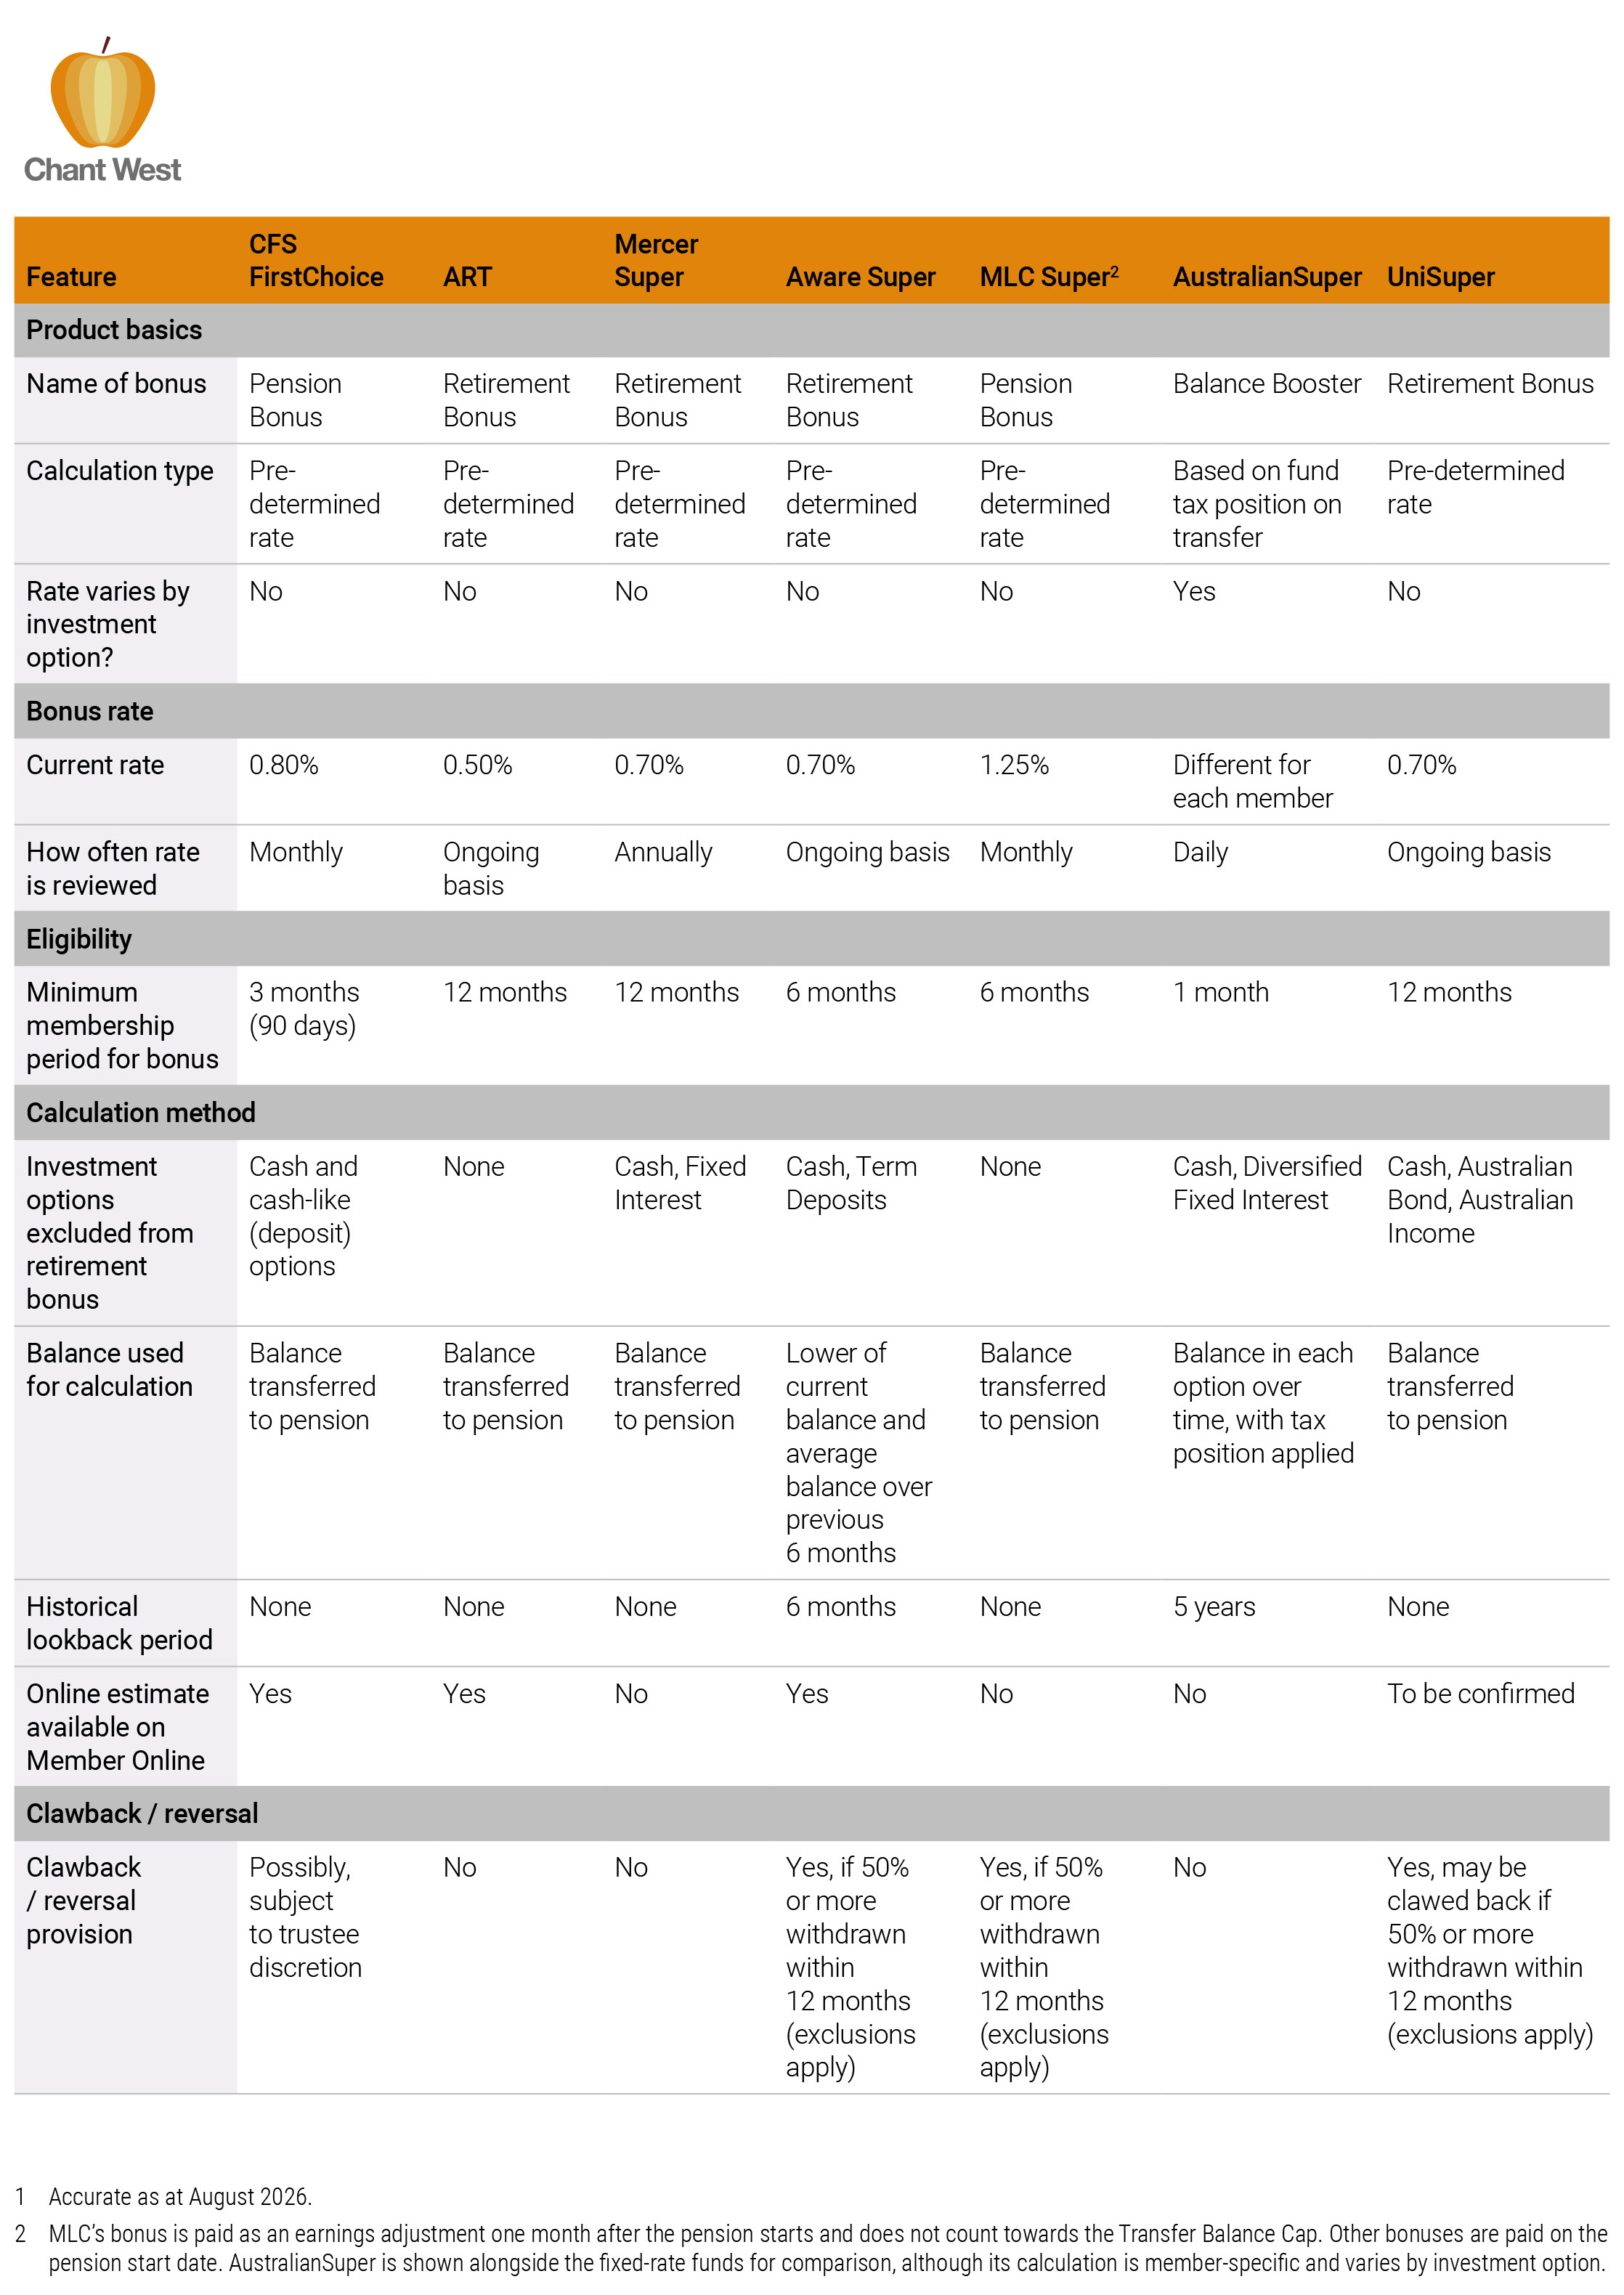
Independent market comparison
This Chant West market comparison shows how the CFS Pension Bonus compares with similar market offers across bonus structure, minimum accumulation period, eligibility requirements, investment restrictions and operational features.
Information and tools

Pension Bonus Adviser Flyer
Discover how the CFS Pension Bonus can help your clients unlock additional retirement income opportunities..
Pension Bonus Adviser Playbook
One part of a complete retirement ecosystem
Retirement Income Optimiser is one capability within CFS Retirement Advantage™, an ecosystem of retirement solutions, specialist expertise, education, tools and implementation support designed to help advisers deliver better retirement experiences.
Talk to us about Pension Bonus
Want to understand how Pension Bonus applies to your clients or walk through a scenario? Leave your details and we'll connect you with the right CFS specialist.
Frequently asked questions
One or more of the transferring FirstChoice super or pre-retirement accounts must have been held for 90 calendar days immediately prior to pension commencement. Additional funds contributed or rolled into the transferring account don't need to satisfy the 90-day rule.
The Pension Bonus is a once-per-lifetime payment. Where a client makes a partial transfer and later opens a second pension, the second event will not attract a Pension Bonus.
No, as amounts transferred to Pension via the SuperFirst Transfer facility are not eligible for Pension Bonus Calculation purposes. This is because the SuperFirst Transfer facility utilises First Sentier Strategic Cash.
Contributions and rollovers from external fund(s) can be combined with an existing eligible FirstChoice Super account, in qualifying investment options, prior to transfer to FirstChoice Wholesale Pension in order to qualify for the Pension Bonus.
The Pension Bonus is paid only once per client and is paid on the first pension started. It is not reversable or transferable to another pension. However, if a client is starting multiple pensions on the same day, then all accounts will be assessed for eligibility and any subsequent Pension Bonus will be applied to all pensions started on that day.
TTRs only qualify for the Pension Bonus when transitioning to an account-based pension as a full retirement phase income stream. Starting a TTR alone doesn’t qualify.
No. The Pension Bonus is not guaranteed and is subject to eligibility criteria, fund rules and applicable product terms. Please refer to the PDS for more details.
No. The Pension Bonus is rules-based. Cash and cash-like options are excluded, SuperFirst transfers are excluded, and eligibility is assessed automatically at commencement. Please refer to the PDS for more details.
Because the Pension Bonus is added to the starting balance, it counts towards the Transfer Balance Cap (‘TBC’). Where a client is commencing a pension and the TBC credit (including the Pension Bonus amount) will result in them being very close to their personal TBC, the amount the client uses to commence the pension will need to be carefully considered.
No. As investments are sold down to cash on notification of death, death benefits paid in the form of pension are not eligible for Pension Bonus.
The trustee reserves the right to reverse the Pension Bonus in certain circumstances.
For more details, refer to the FirstChoice Wholesale Personal Super and Pension Product Disclosure Statement, available here.
Pension Bonus estimates are generally available for eligible clients over the age of 50. This age was chosen as research shows that members over 50 start to engage more with their superannuation and are more likely to commence retirement planning. You can see Pension Bonus estimates for your clients in FirstNet. Eligible clients can also view their estimate via FirstNet and the CFS app.
We're here to help
Get in touch
For adviser services contact us 8:30am - 6pm (Sydney time) Monday to Friday.
FirstTech: 9am - 5:30pm Monday to Friday.
Important information
¹ This assumes your client has not received a bonus previously
² This example is for illustrative purposes only and does not constitute advice. Figures as at 01 August 2026 and subject to change.
³ Any Pension Bonus and buy/sell refunds count towards your client's Transfer Balance Cap. Advisers remain responsible for managing the client's personal cap. Full eligibility criteria are set out in the relevant PDS.
CHANT WEST COMPARISON TABLE DISCLAIMER
© Zenith CW Pty Ltd ABN 20 639 121 403 (Chant West), Authorised Representative of Zenith Investment Partners Pty Ltd ABN 27 103 132 672, AFSL 226872 under AFS Representative Number 1280401 2026. The data provided by Chant West is based on information supplied by third parties and does not contain all the information required to evaluate the nominated service providers, you are responsible for obtaining further information as required. The data provided by Chant West does not constitute financial product advice. However, to the extent that this data is advice it is General Advice (s766B Corporations Act) and Chant West has not taken into account the objectives, financial situation, including target markets of financial products, where applicable, or needs of any specific person who may access or use this data. It is not a specific recommendation to purchase, sell or hold any product(s) and is subject to change at any time without prior notice. Individuals should consider the appropriateness of any advice in light of their own objectives, financial situations or needs and should obtain a copy of and consider any relevant PDS or offer document before making any decision. Data is provided in good faith and is believed to be accurate, however, no representation, warranty or undertaking in relation to the accuracy or completeness of the data is provided. Data provided is subject to copyright and may not be reproduced, modified or distributed without the consent of the copyright owner. Except for any liability which can not be excluded, Chant West does not accept any liability whether direct or indirect, arising from use of this data. Past performance is not an indication of future performance. Full details regarding Chant West’s research methodology, processes, ratings definitions are available at www.chantwest.com.au and Chant West’s Financial Services Guide is available at www.chantwest.com.au/financial-services-guide.